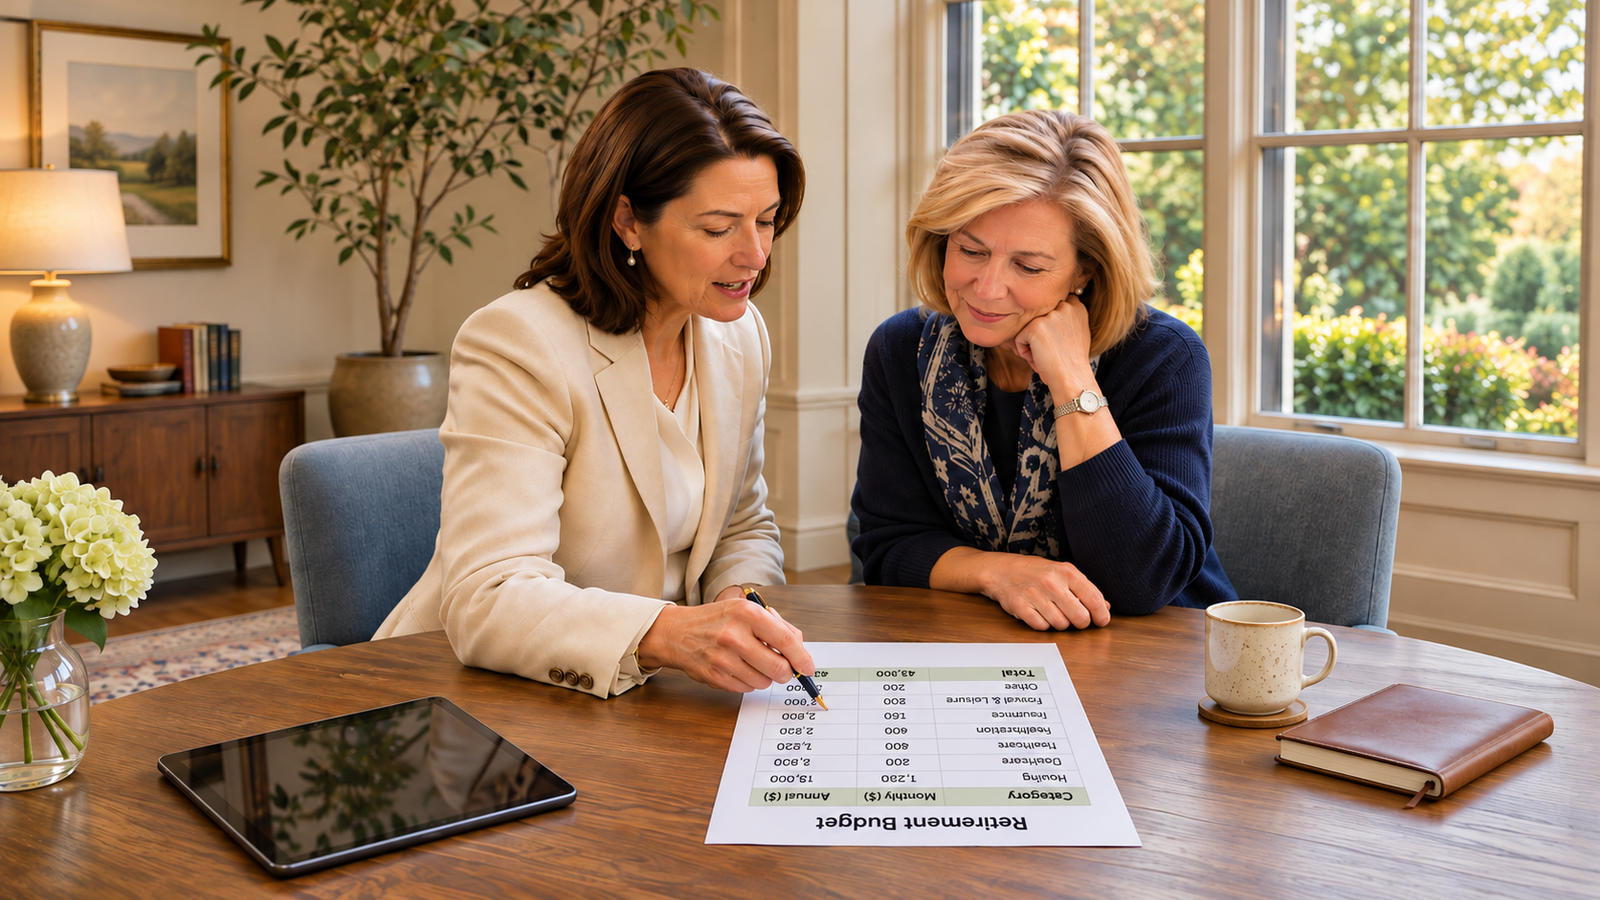
Retirement planning usually begins with what we expect the future to look like. We consider when we would like to stop working, where we might live, how much income we will need and the lifestyle we hope to enjoy. These assumptions provide the foundation for making financial decisions that may need to support us for several decades.
However, even a carefully constructed retirement plan cannot anticipate everything. Changes in health, unexpected family responsibilities, the loss of a partner or a sudden need to relocate can all affect financial circumstances in ways that were difficult to foresee.
These events may influence much more than immediate expenditure. They can change where someone wants or needs to live, how their income is used, which assets remain suitable and who is responsible for managing their finances.
Good retirement planning should therefore do more than prepare for the future we expect. It should also consider whether our financial arrangements can continue to support us when circumstances develop differently from those originally anticipated.
When One Unexpected Event Changes Several Financial Decisions
One of the challenges with unexpected events is that their financial consequences are rarely limited to a single expense.
A change in health, for example, may create additional medical costs, but it could also affect someone’s ability to live independently, their preferred retirement location or the suitability of their existing property. What initially appears to be a healthcare issue can quickly become a decision about housing, income and the accessibility of accumulated wealth.
Similarly, an unexpected family responsibility may require someone to provide financial assistance to a relative, spend more time in another country or reconsider plans that had previously seemed settled.
These developments can create financial decisions that are connected to one another. Selling a property may release capital but also change future living costs. Providing financial assistance to family members may be manageable in the short term but reduce the resources available for retirement income later.
The difficulty is that decisions sometimes need to be made quickly, particularly when personal circumstances are already demanding.
Considering how different parts of a retirement plan depend on one another can help identify where an unexpected change might create wider financial consequences. The objective is not to prepare a detailed response to every possible event, but to avoid arrangements where one disruption forces several difficult financial decisions at the same time.
Ensuring Financial Arrangements Can Still Be Managed
An important part of retirement planning is considering what would happen if someone became temporarily or permanently unable to manage their own financial affairs.
During retirement, financial arrangements may include pensions, investment portfolios, bank accounts, property and insurance policies, potentially held across several countries. While the individual responsible for these arrangements may understand how everything works, a spouse or family member may not have the same knowledge.
This can become particularly difficult following a serious illness, a loss of mental capacity or the death of a partner.
Knowing that financial assets exist is not necessarily the same as being able to access or manage them. Accounts may be held in one person’s name, investment instructions may require specific authorisation and financial institutions may have their own procedures for recognising someone acting on another person’s behalf.
Keeping an organised record of important financial arrangements can make a considerable difference. This might include details of financial institutions, pension providers, insurance policies, professional advisers and the location of relevant legal documents.
It is equally important to consider whether appropriate legal arrangements are in place if someone becomes unable to manage their own affairs. Powers of attorney may allow a trusted person to act during their lifetime, while wills and other estate planning arrangements address what happens after death. The requirements and legal effect of these documents will depend on the jurisdictions involved.
For internationally mobile families, additional care may be required. Legal authority established in one jurisdiction may not automatically be recognised in another, particularly where assets, property or financial institutions are located in different countries.
These arrangements should be considered with appropriately qualified legal professionals, rather than assuming that a document prepared in one country will necessarily be sufficient everywhere.
The purpose is to ensure that financial affairs can continue to be managed when circumstances make it difficult or impossible for the usual decision-maker to act.
Maintaining Financial Options When Circumstances Change
Unexpected developments can sometimes require decisions to be made within a relatively short period.
Someone may need to relocate, change their housing arrangements, provide financial assistance to a family member or meet expenditure that was not anticipated when their retirement plan was established.
In these situations, the structure of accumulated wealth can be just as important as its overall value.
A person may have substantial assets but limited ability to access capital without selling property, surrendering an investment or making changes that carry financial consequences. Others may have more flexibility to meet an unexpected commitment without disrupting their longer-term arrangements.
This does not mean retirement wealth should be kept entirely in readily accessible accounts. Long-term investments, property and other assets may continue to play important roles in supporting retirement objectives.
However, significant financial commitments should be considered alongside the possibility that circumstances may change. Where substantial amounts of wealth are tied to arrangements that are difficult or expensive to alter, responding to an unexpected event can become more complicated.
The objective is to maintain enough flexibility to make considered decisions when circumstances change, rather than being forced into actions that may not be in someone’s longer-term financial interests.
Knowing When to Reassess Your Retirement Plan
Not every unexpected expense or change in circumstances requires a fundamental revision of a retirement plan.
Some disruptions are temporary and can be managed within existing financial arrangements. An unplanned property repair, for example, may affect expenditure in a particular year without materially changing someone’s longer-term financial position.
Other developments can have more lasting consequences.
A permanent change in health, the loss of a significant source of income, a major family commitment or an unexpected change in residence may affect assumptions on which the original retirement plan was based.
In these situations, continuing with the same financial strategy simply because it was previously appropriate may no longer make sense.
A meaningful review should consider how the change affects future income requirements, the availability of capital, existing financial commitments and the suitability of current investments.
It may also be necessary to reconsider decisions that were previously expected to take place much later. A planned property sale, for example, might need to happen earlier, while an anticipated financial gift may need to be postponed if future expenditure has become less certain.
The important distinction is between reacting to an immediate event and understanding its longer-term financial implications.
Taking time to reassess the wider financial position, with professional advice where appropriate, can help ensure that decisions made in response to an unexpected development remain consistent with future financial needs.
Building Resilience Into Retirement Planning
Unexpected events can change financial circumstances quickly, sometimes affecting several parts of a retirement plan at once. Preparing for these possibilities is not about anticipating every difficulty, but ensuring that financial arrangements remain workable when life takes an unexpected direction.
A retirement plan that allows important decisions to be made, assets to be managed and financial priorities to be reconsidered when necessary is better placed to support long-term security, even when circumstances change.